The Smoking Gun: What Evidence Would Determine If Yampolskiy Hacked Competitors, and Does Factor Have It?
A Slack message, a Dropbox link, an access log, an invoice. What the federal record already holds on alleged competitor access, what discovery would have to establish, and why each link in the chain must stand on its own.
12 min readInvestigation · Allegations unadjudicated
01Small evidence, large consequences
In cybersecurity investigations, the most consequential evidence is not always sophisticated. Sometimes it is a single Slack message. A screenshot. A Dropbox link. An invoice. A payment approval. Or an employee who can answer one direct question under oath.
That is the lens through which to read the most serious allegation in the federal lawsuit brought by Factor Cybersecurity and its founder, Jason Thompson, against SecurityScorecard and its chief executive, Aleksandr Yampolskiy. The complaint is primarily a defamation, interference and trademark case. But embedded in its account of why the relationship soured is a claim that, if proven, would matter far beyond this lawsuit: that SecurityScorecard’s CEO accessed a competitor’s platform without authorization and that information obtained that way circulated inside the company.
The central question of this investigation is narrow. Could evidence connecting an alleged third-party account, an intermediary, corporate communications and potential payments establish unauthorized competitor access and executive knowledge? And how much of that chain does Factor actually have today? The honest answer separates five things: documents already available, allegations in federal filings, connections supported by public information, evidence not yet obtained or authenticated, and the consequences that would follow only if the allegations are proven.
02The evidence trail
Any case that the alleged access occurred would have to connect four points. Figure 1 maps them, and it uses four visual treatments on purpose: a solid border for what public documents establish, a dashed border for what is alleged in court filings, a double border for eyewitness accounts, and a dotted border for links that remain unverified. The point of the graphic is the gaps between the boxes, not the boxes themselves.
Figure 1 · The evidence trail: what Factor has and what discovery must establish
Documented
Alleged in a court filing
Eyewitness accounts
Unverified / must be proven
A · Alleged in a court filing
Identified victim company(s)
The competing platform whose systems or information were allegedly accessed. The complaint, ¶¶ 24–26, alleges the access; the company itself has made no public statement.
B · Alleged in a court filing
“Emma Mason” furniture account
An account allegedly used to reach the platform through a VPN, described in October 1–2, 2025 text messages supplied by the plaintiff. Registration and log records are not in the public record.
C · Documented
Lenny Kharitonov
His public LinkedIn profile lists him as CEO of Emma Mason Furniture, and he commented publicly on a Yampolskiy post (The Record). Any role in the alleged access is unverified.
D · Eyewitness accounts
Aleksandr Yampolskiy / SecurityScorecard
According to Jason Thompson, more than a dozen eyewitnesses can attest to executive and corporate knowledge of, and participation in, the alleged access. Those accounts have not yet been presented or tested in court.
The links between them
B → AAccount allegedly used to enter the platformAlleged in a court filing
C → BName match: profile lists him as the furniture company's CEODocumented
C → DPublic social-media interaction onlyDocumented
D → AKnowledge and participation: reported by more than a dozen eyewitnessesEyewitness accounts
Technical records
VPN, authentication, account registration, IP addresses and access logs.
Communications
Slack messages, Dropbox links, screenshots, file metadata and internal correspondence.
Witnesses
Current and former IT, security, engineering and product-management personnel.
Financial records
Vendor invoices, consulting agreements, payments, approval records and accounting entries.
Start with what is in the filed complaint. In paragraph 24, Factor alleges that Yampolskiy told Thompson on multiple occasions that he had paid individuals thousands of dollars to obtain nonpublic information about competitors, and that information obtained that way “was distributed internally through Dropbox links and Slack with warnings not to share it because of the manner in which it had been obtained.” In paragraph 25, Thompson says he personally witnessed Yampolskiy log in to a competitor’s platform from his office computer through a VPN, in view of staff. Thompson says he was not the only one: by his account, more than a dozen eyewitnesses can attest to Yampolskiy’s and the company’s knowledge of, and participation in, the alleged access. Those witnesses have not yet given sworn testimony in the case, but they are the kind of evidence a court treats most seriously. Paragraph 26 alleges, on information and belief, that the information influenced product design, sales strategy and customer presentations.
Those are firsthand allegations made in a pleading signed under Rule 11. They carry more weight than rumor, and they are specific enough to be tested. They are not proof. SecurityScorecard’s July 14, 2026 letter to Thompson does not address these specific allegations, which is not evidence either way, and no court has made any finding.
Next are the plaintiff-supplied text messages from October 1–2, 2025, reproduced in The Record and analyzed in this site’s Emma Mason discovery investigation. In them, Thompson describes a log-in “through a vpn” to a competitor account, screenshots placed “on a Dropbox,” and a Dropbox then shared internally. The messages tie the alleged access to an account associated with a furniture business. They are contemporaneous, which matters, but they are Thompson’s own words, and they have not been authenticated in court.
Then there is public information. Lenny Kharitonov’s LinkedIn profile, captured October 8, 2026, lists him as CEO of Emma Mason Furniture, and a separate capture shows him commenting on a public Yampolskiy post (The Record). That establishes a name match and a public acquaintance. It does not establish that Kharitonov registered or used any account, that he knew of any access, or that he received anything. He is not a party to the case and is entitled to the presumption that he did nothing wrong.
Evidence matrix · what exists, and what would test it
Of everything in paragraph 24, the most testable detail is the distribution channel. People forget conversations; workplace platforms rarely do. If confidential competitor screenshots were shared through a Dropbox link posted in Slack, the trail would include the message, the link, the folder’s sharing history, the files themselves and their metadata: who uploaded them, when, from which device, and who opened them.
A single contemporaneous message from Yampolskiy containing such a link could do work that no amount of testimony can. It could show distribution (the material moved inside the company), possession (the sender had it), and, depending on the words around it, knowledge of where it came from or direction to use it. That is why the question Factor’s lawyers would most want answered under oath is simple:
“Did Aleksandr Yampolskiy ever send you a Slack message containing a Dropbox link with screenshots or other confidential information belonging to a competitor?”
Asked of the right witnesses, that question has only a few answers, and each one is useful. A “no” from people positioned to know narrows the allegation. A “yes” sends the parties to the records. An “I don’t recall” invites the records anyway.
To be clear: no such message has been produced in this case, and this site has seen none. Its significance, if one exists, would depend on four things. Authenticity: whether the message and files are what they purport to be under Federal Rule of Evidence 901. Provenance: where the screenshots came from, and whether they were obtained from the competitor’s platform at all. Authorization: whether whoever captured them was permitted to see that material. And the sender’s knowledge: forwarding a file is not the same as knowing how it was obtained.
05Following the money
Paragraph 24 also alleges payments: “thousands of dollars” to individuals for nonpublic competitor information. Money is often where an evidentiary chain either hardens or breaks, because companies record it. Financial discovery could test whether corporate resources funded any of the alleged activity, through questions to current and former chief financial officers, accounts-payable staff and anyone who approved vendor spending:
Did SecurityScorecard pay Lenny Kharitonov, Emma Mason Furniture, or any associated entity?
Were consulting agreements or invoices created for any such payments?
Who approved the relevant expenditures?
Were any financial records modified or reclassified, and why?
Were intermediaries or additional organizations used?
Did any executive receive information or services resulting from those expenditures?
Nothing in the record shows that any such payment occurred or that any record was altered, and this article does not assume either. The point is structural. An authenticated payment record standing alone shows a financial relationship, nothing more. Combined with communications showing what was being paid for, and technical logs showing who entered a system and when, it becomes part of a chain in which each link supports the others. Absent the other links, it proves very little.
06Why it matters to the retaliation lawsuit
Factor’s lawsuit is not, at bottom, a hacking case. Its claims are for defamation, tortious interference, false advertising and related relief. The alleged competitor access enters as context: the complaint says Thompson reported the conduct internally and to SecurityScorecard’s board shortly before resigning, and that Yampolskiy “threatened Thompson and retaliated against him” after learning of the report (¶¶ 2, 27). Thompson’s position, reflected in the timeline on this site, is that the campaign against Factor intensified after the alleged Emma Mason access route was shut down. That sequence is his account; the filed complaint does not itself plead a shutdown date.
Sequence is not causation. That one event followed another does not prove the first caused the second. But evidence about the earlier conduct could become relevant to motive, to what Yampolskiy knew about Thompson’s knowledge, to the relationships involved, and to whether later accusations against Factor were made in good faith. Under Rule 401, evidence is relevant if it makes a fact of consequence more or less probable. Rule 404(b) bars using other acts to show character, but permits them to show motive, intent or knowledge.
Discovery has its own limits. Rule 26(b)(1) allows discovery of nonprivileged matter relevant to a claim or defense and proportional to the needs of the case. SecurityScorecard would likely resist broad requests as a fishing expedition into a third party’s affairs, assert attorney-client privilege over internal investigations (protected under Rule 502 against inadvertent waiver), and seek protective orders over any competitor material. Admissibility at trial is a separate fight again. Getting a document produced is not the same as getting it in front of a jury.
07Riverwood Capital and the investor question
Any allegation of executive misconduct at a venture-backed company raises a question about the people who financed it. SecurityScorecard’s historical financing is a matter of public record. Riverwood Capital led the company’s $50 million Series D round in June 2019, and was listed among existing investors participating in the $180 million Series E round in March 2021. Riverwood’s own portfolio page lists co-founder and managing partner Francisco Alvarez-Demalde and partner Joe De Pinho on its SecurityScorecard investment team. De Pinho has been described as joining SecurityScorecard’s board in connection with the Series D investment; this site has not independently confirmed his board dates.
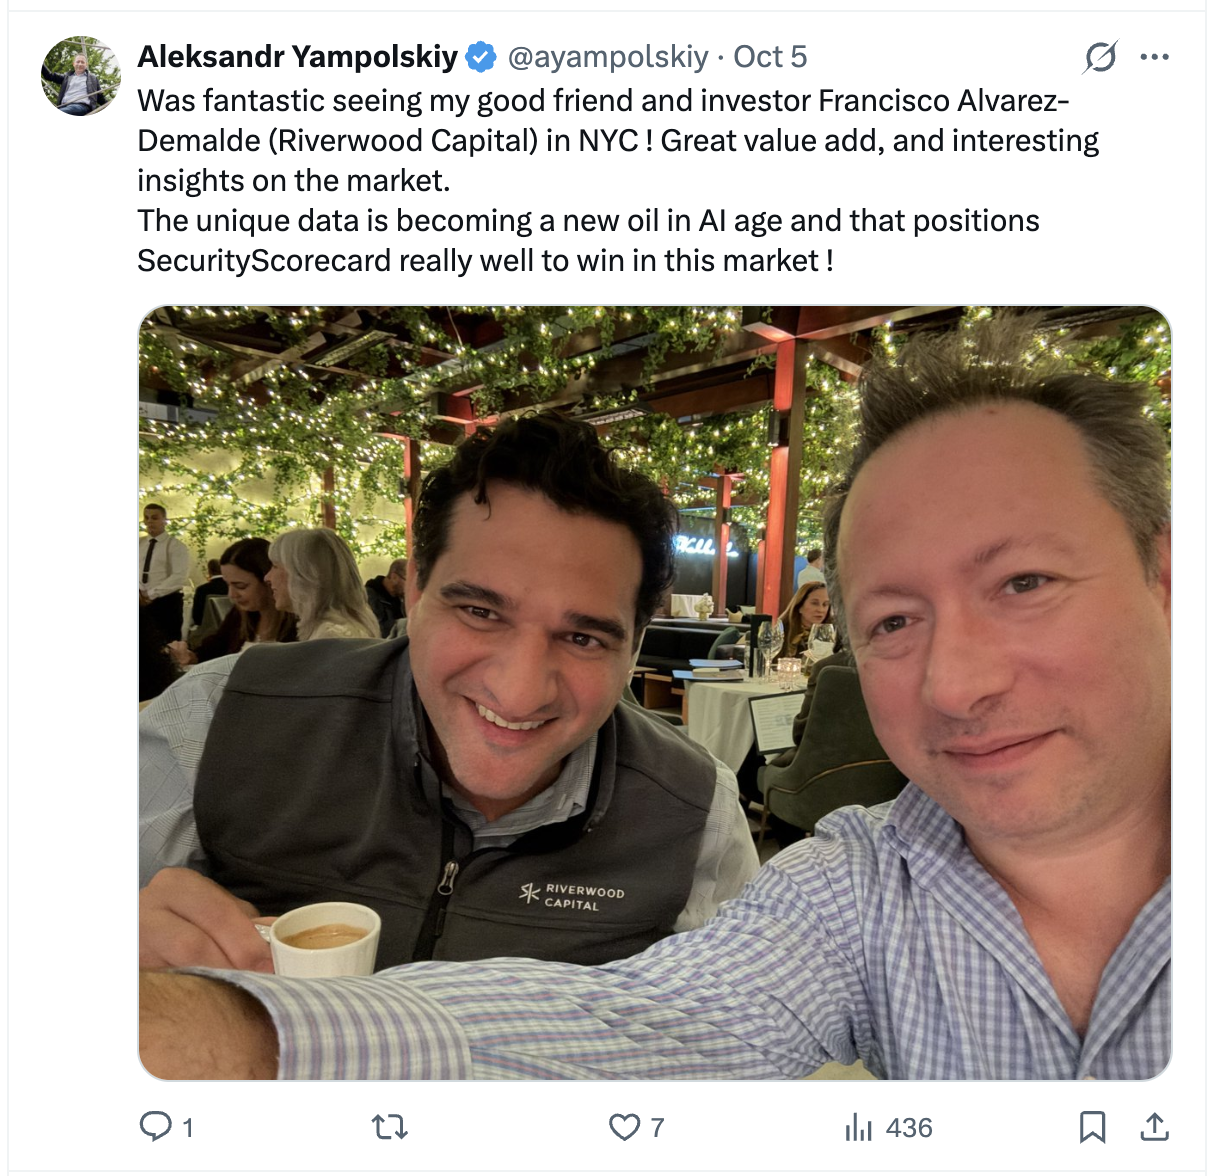
Aleksandr Yampolskiy’s October 5, 2026 post describing a meeting with Riverwood Capital co-founder Francisco Alvarez-Demalde. The post documents their publicly acknowledged relationship, not knowledge of or involvement in the alleged conduct. Source: X, @ayampolskiy; screenshot supplied by the site owner.
Transcript: Aleksandr Yampolskiy (@ayampolskiy), Oct 5: “Was fantastic seeing my good friend and investor Francisco Alvarez-Demalde (Riverwood Capital) in NYC! Great value add, and interesting insights on the market. The unique data is becoming a new oil in AI age and that positions SecurityScorecard really well to win in this market!” Photo: a selfie of Yampolskiy and Alvarez-Demalde, who wears a vest with the Riverwood Capital logo, at a restaurant. Shown: 1 reply, 7 likes, 436 views.
On October 5, 2026, after the Factor lawsuit was filed, Yampolskiy posted a photo with Alvarez-Demalde, calling him a “good friend and investor” and adding that “unique data is becoming a new oil in AI age.” The post shows a close, publicly acknowledged relationship. It does not suggest that Riverwood, Alvarez-Demalde or De Pinho knew of or had any involvement in the alleged conduct, and this article makes no such claim.
What it does raise is the question every sophisticated investor would ask if the allegations were ever substantiated. Directors and major investors would reasonably want to know what the board was told and when; whether any internal investigation followed Thompson’s report; whether the company’s representations in later fundraising, customer contracts or insurance applications were accurate; and whether material legal exposure was disclosed to new investors. Those are governance questions, and in Delaware, oversight duties attach once red flags are reported to a board.
08From 100 to 30: the valuation question
The financial backdrop is already difficult. As this site’s Board Spotlight documents, secondary-market indications reported by StockAnalysis sit roughly 70% below the 2021 round price on a nominal comparison. Figure 2 indexes that comparison: 100 for the historical reference value, 30 for the illustrative marked-down value.
Figure 2 · From 100 to 30: the valuation question
Historical reference value (2021 round, indexed)100
Illustrative marked-down value (secondary indications)30
−70%
Indexed, illustrative company-level comparison based on secondary-market indications reported by StockAnalysis, discussed in this site’s Board Spotlight. It is not an audited valuation and does not measure the value of any particular investor’s holdings, including Riverwood Capital’s, which depend on share class, entry price and preferences.
Two cautions. First, that is a reported, company-level estimate drawn from secondary indications, not an audited valuation. Second, it says nothing precise about any one investor. Riverwood’s holdings depend on the class of shares, the price it paid and its liquidation preferences; this article does not claim Riverwood’s investment has lost 70%, or any specific amount.
Substantiated legal exposure would put further pressure on that number through channels that rarely wait for a verdict. Customers in regulated industries ask about litigation in vendor-risk reviews. Insurers commonly exclude deliberate or criminal acts. Lenders watch litigation and material-adverse-change covenants. Acquirers price contingent liabilities and then discount for uncertainty itself, and new investors negotiate tougher terms. None of that is evidence of current harm; it is how the risk would transmit if the allegations gained support.
09Potential personal and investor liability
Everything in this section is conditional. If evidence established that an executive personally participated in unauthorized access, several statutes could come into play. The Computer Fraud and Abuse Act, 18 U.S.C. § 1030(g), gives a civil action to anyone who suffers qualifying loss from unauthorized access, generally at least $5,000 in a year. The Defend Trade Secrets Act and state trade-secret laws reach misappropriation of information that qualifies as a trade secret, with exemplary damages possible only for willful and malicious conduct. Corporate officers can be held personally liable for torts they personally commit or direct, even when acting for the company. Criminal statutes, including § 1030 and 18 U.S.C. § 1832, are a separate track that only prosecutors can pursue; no charges are publicly known.
Securities law raises a different question. Private-company stock is still a security, and Rule 10b-5 prohibits materially false statements or omissions in connection with buying or selling it. If fundraising materials made material misrepresentations about how the company built its products or what legal risks it faced, investors who relied on them could have claims. That would require proof of materiality, falsity, the speaker’s state of mind, reliance and loss.
Finally, there is no automatic clawback. Recovering proceeds from earlier secondary share sales or executive cash-outs would require a specific legal basis: a contractual clawback provision, a fraud or fiduciary-duty claim, or a statutory remedy. None of these is triggered by allegations alone, and none has been asserted.
10Does Factor have the smoking gun?
Not yet, at least not in public. What Factor has is a detailed, firsthand set of allegations in a federal pleading, more than a dozen eyewitnesses who, by Thompson’s account, can speak to executive knowledge and participation, contemporaneous text messages that describe the mechanism, and public records that make a name connection plausible. What it does not yet have in the public record is any of the original artifacts: the access logs, the account registration, the Slack messages, the Dropbox files, the invoices or the payments.
The critical questions are whether those records exist, whether they can be authenticated, and what they actually establish. One Slack message could establish distribution. One set of access logs could establish who entered a system. One payment record could establish a financial relationship. On executive knowledge, Factor says it already has more than a dozen eyewitnesses; once sworn, their testimony could connect those records to the people who directed the access. But each link must be independently supported, and a chain is only as strong as the weakest one.
If the alleged operation occurred, where are the messages, files, access logs, and payments? Who created them, who received them, and who authorized the activity?
Those are the questions that could determine whether Factor’s allegations remain contested assertions or become provable facts.
The FBI’s Boston Cyber Task Force interviewed multiple witnesses about Yampolskiy’s alleged access to Bitsight and requested evidence tracing Bitsight material into SecurityScorecard’s product.
A day after his firm sent preservation letters to a Factor executive and an advisor, Yampolskiy’s defense attorney Michael Yaeger demanded that the Chronicle come down. His email identified no factual error in the articles he attached.
On November 19, Carlton Fields attorney Michael D. Margulies emailed a Factor Cybersecurity executive and an advisor at their personal addresses. They were already represented by counsel.